
Since April 2026, Brink's has been in a holding pattern, posting a small return of 0.7% while floating around $103.47. The stock also fell short of the S&P 500’s 17.5% gain during that period.
Is now the time to buy BCO? Find out in our full research report, it’s free.
Why Does Brink's Spark Debate?
Known for its iconic armored trucks that have been a fixture in American cities since 1859, Brink's (NYSE:BCO) provides secure transportation and management of cash and valuables for banks, retailers, and other businesses worldwide.
Two Things to Like:
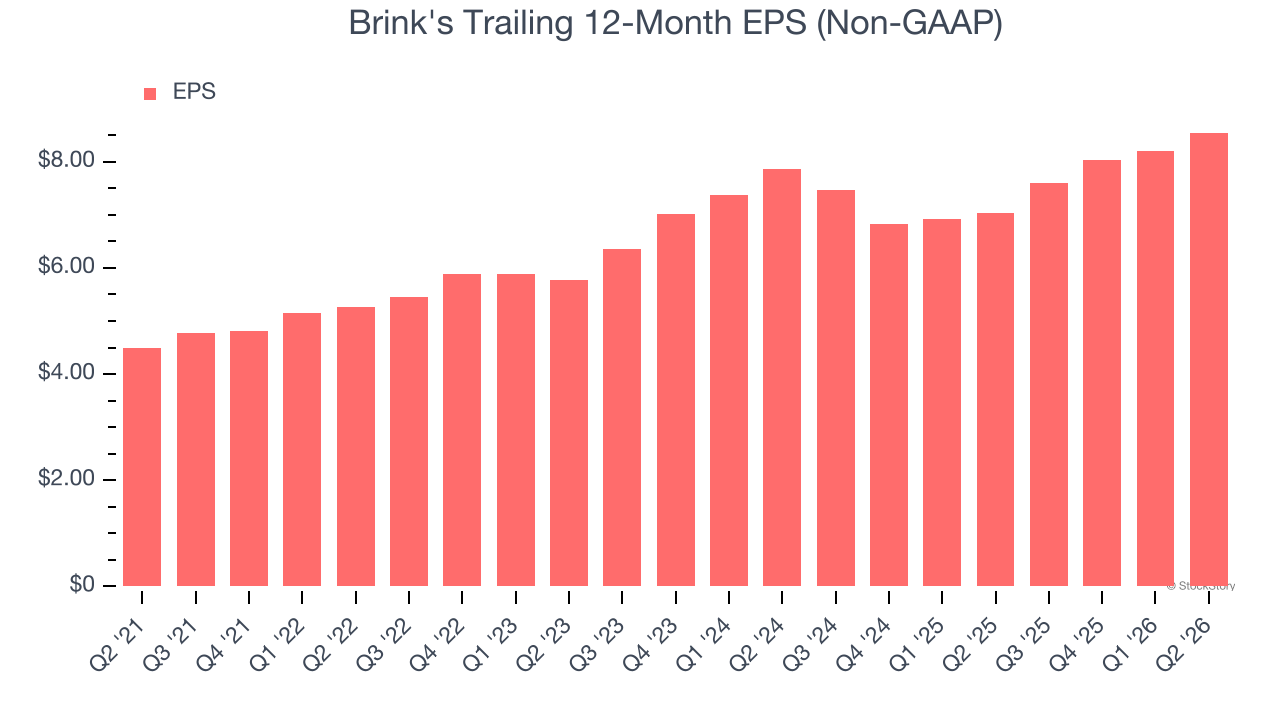
1. Outstanding Long-Term EPS Growth
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Brink’s EPS grew at 13.7% compounded annual growth rate over the last five years, higher than its 6.4% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
2. New Investments Bear Fruit as ROIC Jumps
A company’s ROIC, or return on invested capital, shows how much operating profit it makes compared to the money it has raised (debt and equity).
Fortunately, Brink’s has increased over the last few years. This is a great sign when paired with its already strong returns. It could suggest its competitive advantage or profitable growth opportunities are expanding.
One Reason to Be Careful:
Projected Revenue Growth Is Slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Brink’s revenue to rise by 3.4%, a slight deceleration versus its 6.4% annualized growth for the past five years. This projection doesn’t excite us and suggests its products and services will see some demand headwinds. At least the company is tracking well in other measures of financial health.
Final Judgment
Brink’s positive characteristics outweigh the negatives. With its shares underperforming the market lately, the stock trades at 10.6× forward P/E (or $103.47 per share). Is now the time to initiate a position? See for yourself in our full research report, it’s free.
High-Quality Stocks for All Market Conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.